In a share sale or investment agreement, the parties set a price according to their own arrangements under the principle of freedom of contract. Naturally, given potential tax consequences, the sale price must not differ significantly from market terms. A simple share valuation, a few negotiating meetings and a specific figure in the contract might seem enough. But is it?
If circumstances change
For straightforward transactions, there is nothing to prevent a fixed sale price. Remember, however, that incorrectly determining the value of the shares, the sale price or the payment method can have far-reaching consequences. Therefore, in most cases it is worth analysing this issue thoroughly and choosing a calculation formula based on one of the pricing methods below.
When preparing a share purchase offer, consider one of these price mechanisms: (1) price adjustment, (2) earn-out and (3) locked box. Each type of clause carries both benefits and risks.
Completion accounts — the position at completion
Under the completion accounts mechanism, the price is adjusted to reflect the company's financial position on an agreed date, usually completion. The accounts may be prepared later, but describe the position on that date, not the achievement of forecasts in subsequent months.
The key issues are metric definitions, accounting policies, preparation and review of the accounts, and resolution of differences. The mechanism does not in itself require the existing management board to remain.
Earn-out — a price linked to future performance
An earn-out links part of the price to results or other agreed targets achieved after the transaction. The seller's continued involvement in management is common, but does not define the mechanism.
It is a form of commission for the seller, whose amount depends on the company's subsequent performance. This may be reflected in improved financial results, measured by EBIT/EBITDA, net profit or turnover, or in other objectives, such as launching a product or achieving a particular market position.
This appears best suited to transactions involving high-potential companies capable of significantly improving their results and market position over a short period, where appropriate involvement of the existing business leaders is essential. Like price adjustment, it also offers the buyer some protection against hastily investing too much in a company where material risks have been identified that may affect its economic position after completion.
Protection when fixing the sale price
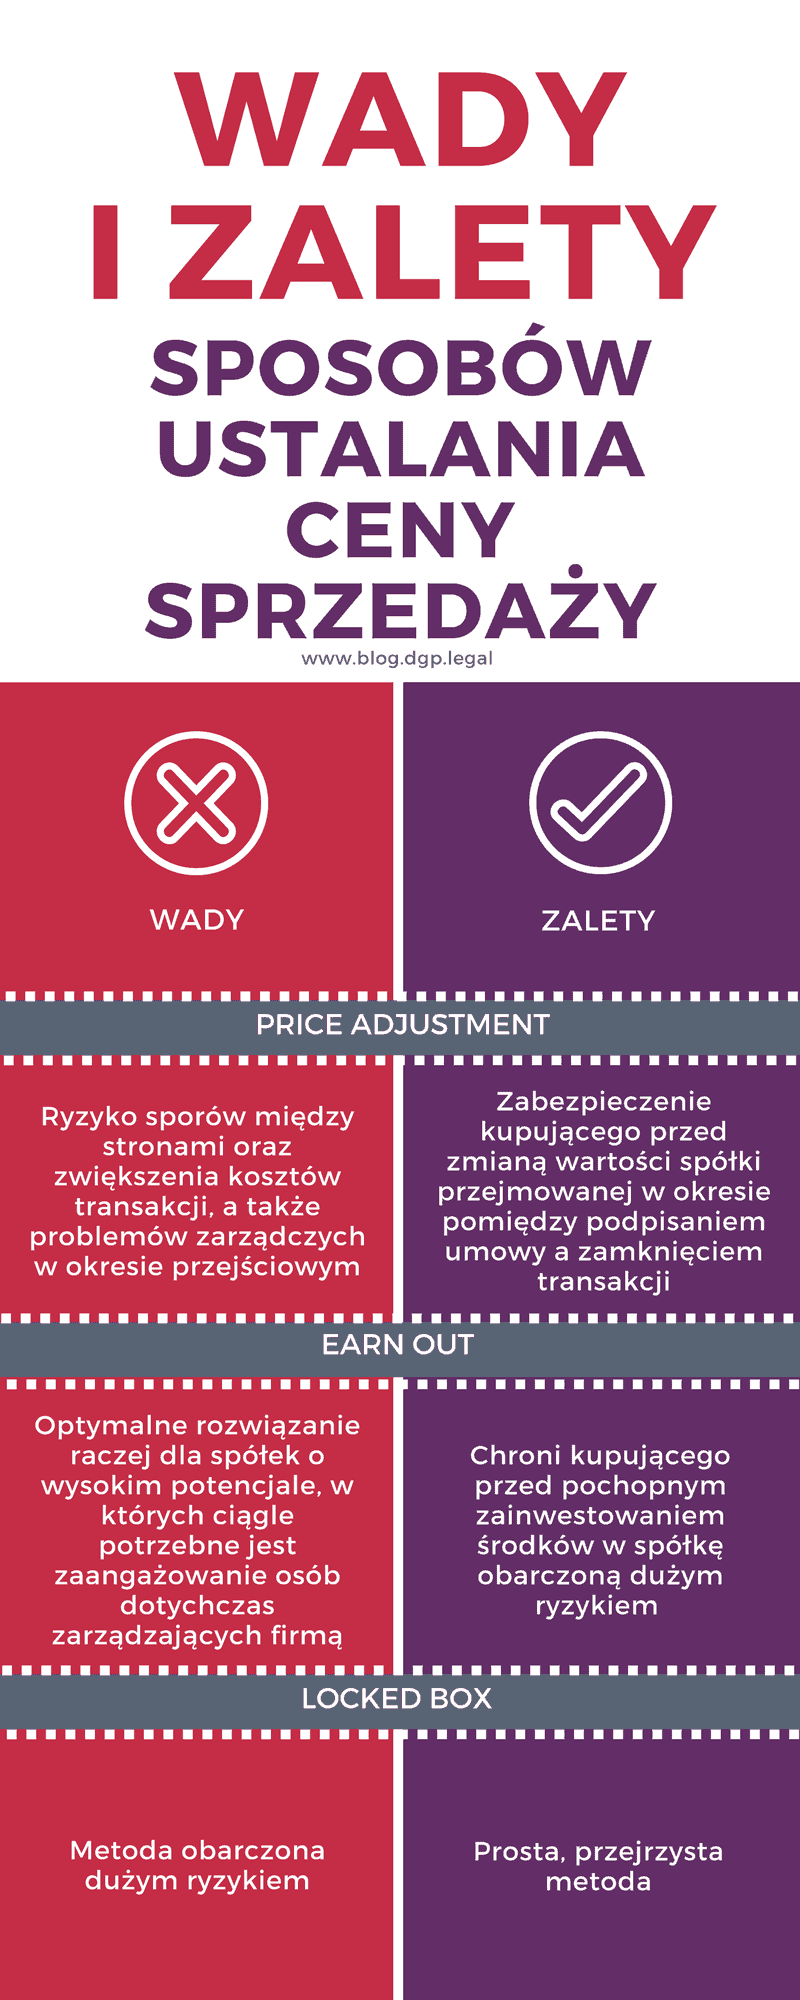
A locked box bases the price on historical financial information at an agreed date, not necessarily the signing date. Safeguards against unauthorised transfers of value to the seller before completion are important (leakage).
A locked box is not inherently the riskiest solution. The choice depends on data quality, business predictability and negotiated safeguards. Every mechanism requires the economic assumptions to be translated consistently into contractual terms.
Act prudently
This brief analysis shows that carefully considered settlement terms with the seller can protect the buyer against substantial financial loss and against paying a price unsupported by the company's future results.
The key in each transaction appears to be assessing the risk of fluctuations in the target's economic position and drafting clear, detailed contractual provisions for verifying the sale price.