What are PPK?
Polish Employee Capital Plans (PPK) are designed for long-term saving, with contributions from employees, employers and the state. The basic contribution financed by the employer is 1.5% of remuneration, while the employee’s contribution is 2%. These figures must not be reversed. If the statutory conditions are met, employees may reduce their basic contribution, but not below 0.5%. Both parties may also make additional contributions.
The fourth implementation phase
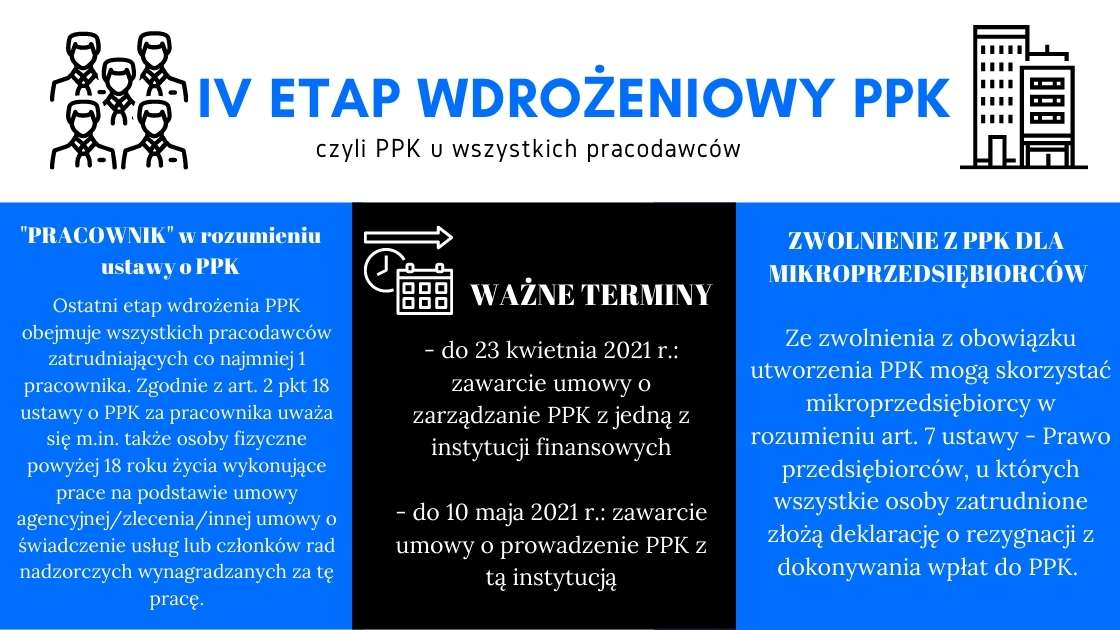
The final phase of implementing the Employee Capital Plans Act began in January 2021. It covers all employers, including those with just one employee. For the purposes of the PPK Act, an employee also includes individuals aged 18 or over working under an agency agreement, a contract of mandate or another services agreement, as well as, among others, supervisory board members paid for carrying out those functions.
Important deadlines for employers in 2021
The dates below document the historical PPK implementation phase in 2021. They are not implementation deadlines for employers starting operations today.
- by 23 April 2021 a PPK management agreement must be concluded with one of the entities, or financial institutions, operating the programme, such as an insurance company. A list of entities is available at: https://www.mojeppk.pl/lista-instytucji-finansowych.html. Under Article 7 of the Act, the financial institution should be selected in agreement with the employer’s employee representatives or, in the first instance, the workplace trade union, if one operates there.
- by 10 May 2021 a PPK participation agreement must be concluded with that institution.
Who does not have to introduce PPK?
Sole traders are not required to establish this savings system, provided they do not employ staff within the meaning of the PPK Act.
Under Article 13 of the PPK Act, microenterprises may be exempt from introducing PPK. All persons employed by them must first submit declarations opting out of PPK contributions.
A microenterprise is an undertaking within the meaning of Article 7 of the Polish Entrepreneurs’ Law that met both of the following conditions in at least one of the last two years of activity:
- it employed fewer than 10 people on average over the year;
- its annual net turnover from sales of goods, products and services and financial operations did not exceed the PLN equivalent of EUR 2 million, or its total balance sheet assets at the end of one of those years did not exceed that amount.
Recommendation
Although employees can opt out of this savings system, entering into a PPK management agreement is recommended. Doing so entails no additional charges. Either of two situations may arise at any time:
- an employee who previously opted out may later apply to make PPK contributions;
- the employer may hire someone new who applies to make PPK contributions.
The employer will then be required to establish PPK. By concluding the agreement now, however, it will already have completed the first implementation step.