A shareholder’s fundamental rights include sharing in the company’s profits, usually through dividends. Dividend policies differ widely between companies for strategic or tax reasons. Dividend entitlements can, however, be much more complex where different forms of preferential rights are involved. One particularly interesting example is ‘tracking stocks’, known in Polish as ‘following shares’, although ‘tracking shares’ might be a better translation.
Regular dividends are not for everyone
Companies controlled by the state or local authorities, often monopolists or operating in oligopolies, for example public utility providers, pay dividends regularly. These serve as a kind of substitute for taxation.
Conversely, it would be unreasonable to expect dividends from businesses that reinvest all their profits, whether as a matter of principle or because market realities require it. The best example is Berkshire Hathaway: Warren Buffett has always argued eloquently why dividends are not in shareholders' interests. Other examples include Alphabet, or Google, although its story is somewhat more complicated because of the notorious Class B shares, as well as Amazon, Facebook and Big Pharma companies.
For years, Steve Jobs explained that dividends were a last resort, since Apple's cash reserves gave the company exceptional security and flexibility in responding to changes in its business environment. For technology companies, a first dividend is also often an unwelcome signal to investors that the company has matured and can no longer be expected to grow as rapidly as before.
Tracking stocks: a little theory
Dividends on tracking stocks depend on the financial performance of a particular part or segment of the business, a subsidiary or a division, rather than the company's overall performance. Their holders are formally co-owners of the parent company, like other shareholders, and payment of the dividend remains exposed to risks associated with the company's overall results. The company must define the terms on which financial results are allocated to the tracking stocks; in certain circumstances, these may change after the shares have been issued.
How does this work in practice?
Companies usually offer tracking stocks to the public as an additional option for shareholders alongside the main ticker. They are generally issued in one of three ways: as additional shares for existing shareholders through a dividend in kind; as consideration for the owners of an acquired company; or through a special form of quasi-IPO. This can be attractive for companies operating in several substantially different market segments, or where one business segment is growing much faster than the others and the company believes the market is not valuing it properly.
Issuing tracking stocks provides a market valuation for a subsidiary, which may matter for options granted to its managers or for a sale transaction involving a partial share exchange.
Tracking stocks also give investors an attractive alternative where they would not be interested in the company's core business, for example because it lacks prospects for rapid growth. Their issue acts as a substitute for a spin-off or split-off and may also precede an actual split-off, as in the AT&T Wireless Group transaction in 2000.
Examples of issues
The first issues of this kind were made by General Motors in 1984 in connection with its acquisition of Electronic Data Systems, a pioneer in IT outsourcing, and then in 1985 for Hughes Electronics. Tracking stock issues are regarded as a periodically recurring fashion.
At one time, telecommunications companies, including AT&T and Sprint, issued shares tracking mobile operators within their structures, while Alcatel Group issued them for its optoelectronics segment. Tracking stocks have never been particularly popular. Only a few dozen issues can be identified over more than thirty years, including projects by Disney, Applera, Genzyme, Cablevision, WorldCom and Sony. In Europe, apart from Alcatel, they have been virtually unknown.
An example closer to home is New World Resources, listed in London, Prague and Warsaw, which unfortunately is now approaching the end of its life. Built under the Czech model of consolidation and privatisation of the coal industry, NWR issued Class A and Class B shares tracking, respectively, the results and economic value of its coal division, responsible for extraction and processing, and its property division, which managed land and surface infrastructure as an intra-group service.
Although tracking stocks were predicted to disappear altogether as a relic of the 1990s, new examples continue to emerge. One is the issue associated with Dell's acquisition of EMC Corp. in 2016, interesting because of its multi-tier structure. Dell's tracking stocks are linked to the results of VMware, then an EMC subsidiary in which it held more than 80%; the remaining 19.9% of VMware shares continue to trade on the NYSE under ticker VMW.
In 2015, US media group Liberty Media proposed that shareholders exchange their existing shares for three classes of tracking stocks corresponding to the group's business divisions: Sirius XM Holdings Inc., Liberty Braves and Liberty Media. The purpose was to make the business more transparent while retaining the synergies and benefits of keeping the divisions within one group. A similar purpose underlay the 2014 share restructuring of Fidelity National Financial, a financial conglomerate in the property sector.
In 2016, Liberty Media made its high-profile acquisition of Formula One Group, the company responsible for promoting and commercially exploiting rights associated with Formula 1 racing. The acquisition was accompanied by an issue of Formula One Group tracking stocks, listed on NASDAQ as FWONK. Fantex has also created an interesting business model based on tracking stocks, issuing share classes linked to contracts with sports stars. In return for an upfront payment, athletes sell rights to a small portion, usually around 10%, of their income from sporting contracts, advertising and other activities associated with their sporting status.
Finally, in 2017, following the sale of its internet businesses to Verizon, Yahoo was effectively reduced to an alternative investment in e-commerce giant Alibaba Group. Given that Yahoo's assets then consisted mainly of a 15% stake in Alibaba, the June 2017 renaming of Jerry Yang's company as 'Altaba' — 'alternative Alibaba'? — can only be seen as an expression of humility and respect towards investors. Altaba shares became a form of tracking stock.
Tracking stocks: examining the components
To conclude, let us recap the typical features of tracking stocks on the basis of historical examples and consider whether they can be issued under Polish law.
As regards voting at general meetings, tracking stocks carry no preferential rights and quite often are non-voting shares, depending on the circumstances and reasons for their issue. Any voting preferences or restrictions are sometimes linked to differences in market value between tracking stocks and ordinary shares. Although tracking stocks follow the performance of a segment or subsidiary, dividend payments still depend on the results of the whole company and the availability of cash.
The company is not legally obliged to pay regular dividends; any expectations in this regard can arise only from non-binding dividend-policy statements. Participation in the company's assets on liquidation is sometimes tied to the market value of the tracking stocks when liquidation begins, but this is not a rule. A tracking stock holder is also usually entitled to receive specified assets or the proceeds from their liquidation.
Tracking stock holders usually cannot exchange them for ordinary shares, whereas the company may convert them into ordinary shares, as has happened with most tracking stock issues. If the company disposes of the business associated with the tracking stocks, they are repurchased or converted into ordinary shares, potentially with a one-off premium.
Tracking stocks and Polish legislation
Can tracking stocks be issued in Poland? The relatively rigid framework of the Polish Commercial Companies Code and its extensive restrictions on creating new legal structures, often of questionable practical logic, make this difficult.
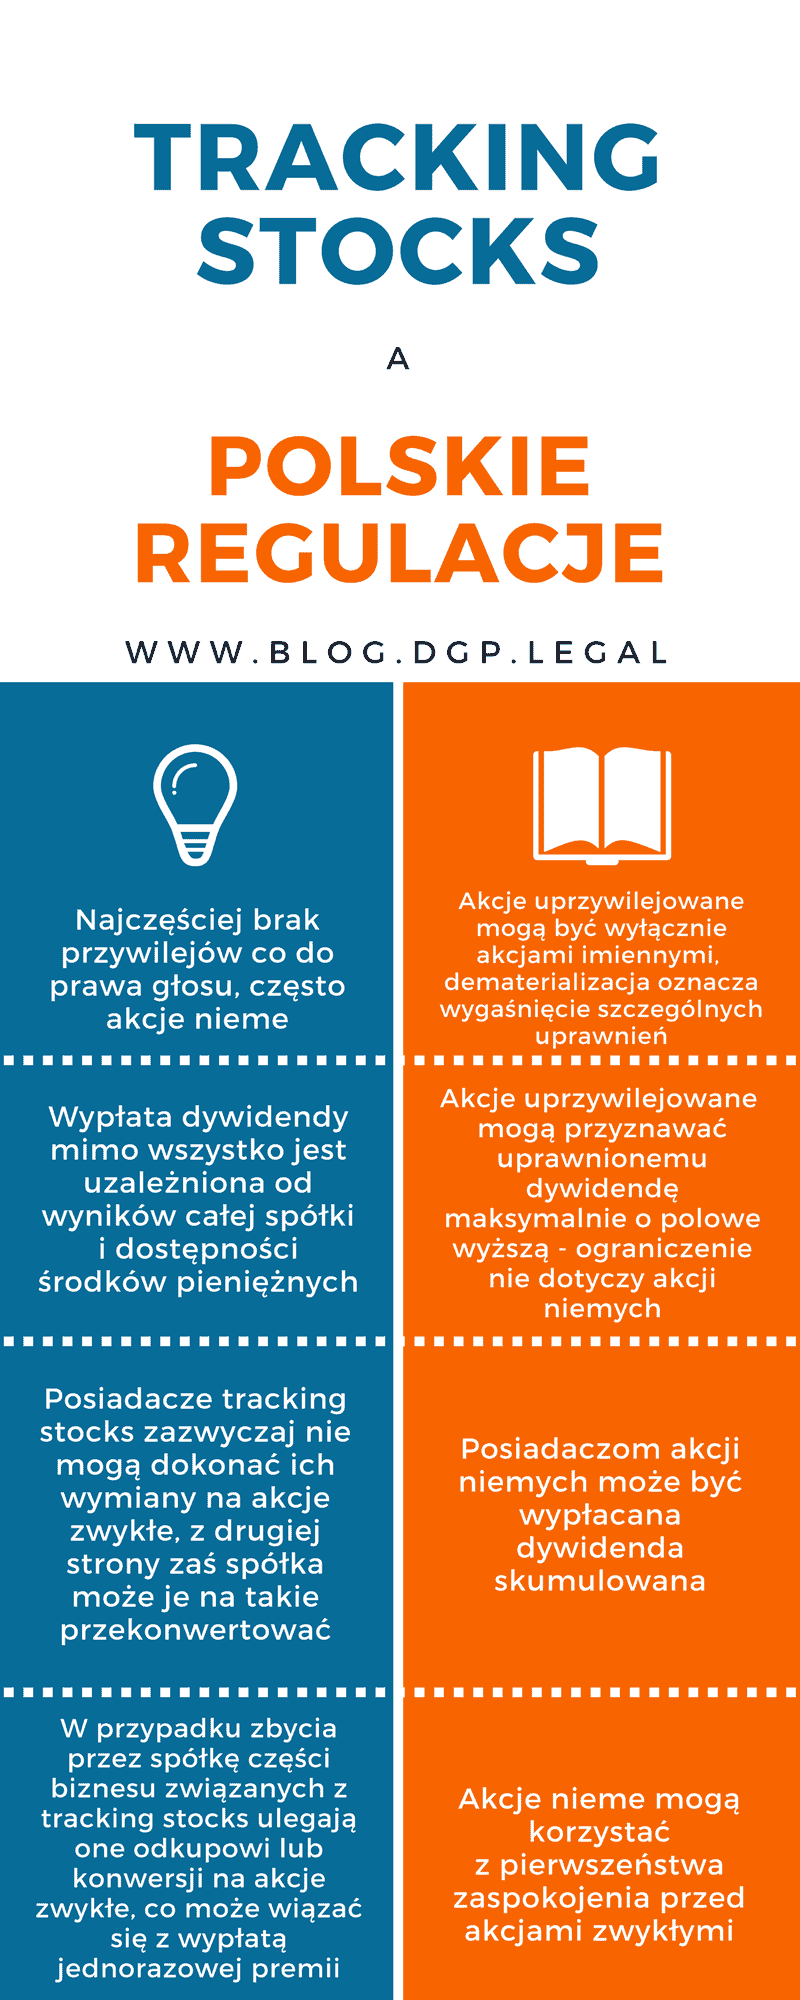
First, under Article 351 § 1 of the Polish Commercial Companies Code (KSH), shares carrying special rights may only be registered shares, and dematerialisation would extinguish those rights. The Code expressly provides for this in relation to preferential voting rights in Article 352, but Article 351 § 1 permits the consequence to be extended to all special rights attached to a share. In addition, under Article 353 § 1 KSH, dividend preference shares may entitle their holder to a dividend no more than one-half higher than that payable to holders of non-preference shares.
Tracking stocks in a Polish joint-stock company would therefore have to be non-voting shares, to which the restrictions above do not apply. Their holders may receive cumulative dividends, meaning dividends not paid, or paid only in part, in previous years. Non-voting shares may also rank ahead of ordinary shares for payment. Apart from the absence of voting rights, except on resolutions materially changing the company's business, they allow all other rights to be exercised, in particular convening and attending general meetings, exercising other corporate and economic rights and challenging general-meeting resolutions.
Apart from New World Resources, which was incorporated in England and Wales, tracking stocks have not appeared on our market. Attempts to offer non-voting shares — Marvipol's public offer in 2012 and Tauron's offer to the State Treasury in 2015 — were unsuccessful. Nevertheless, given the theoretical absence of legal barriers, we may yet see this type of instrument in Poland.